
- Structured Settlements
- What are Structured Settlements
- Best Structured Settlement Buyers
- How Selling Works
- Eligible Cases
- Eligibility Criteria
- Structured Settlement Regulations
- J&J Settlement
- Maui Wildfire Settlement
- Types of Structured Settlements
- Guaranteed Structured Settlements
- Increasing Structured Settlements
- Deferred Structured Settlements
- Life-Contingent Structured Settlements
- Future Lump Sum Settlements
- Annuities
- What Is An Annuity
- Guide to Selling an Annuity
- Income Annuities
- How Are Annuities Taxed?
- 7 Common Annuity Mistakes & How to Avoid Them
- Annuity Beneficiaries
- Types of Annuities
- Fixed Annuities
- Fixed Index Annuities
- Variable Annuities
- Immediate Annuities
- Deferred Annuities
- Registered Index-Linked Annuity
- Pre-Settlement Funding
- What is Pre-Settlement Funding
- How Pre-Settlement Funding Works
- Eligible Cases for Pre-Settlement Funding
- Pre-Settlement Funding Criteria
- Pre-Settlement Funding Regulations
- Types of Pre-Settlement Funding
- Non-Recourse Cash Advances
- Structured Pre-Settlement Funding
- One-Time Lump Sum Cash Advances
- Compounding Interest Funding
- Flat-Fee Structured Funding
- Structured Settlement Calculator



One specialist stays with you from your first call through funding.
November, 2026
“Will I owe the same amount if my case takes another year?”
Ask that before accepting a flat-fee funding offer. A fee fixed through repayment stays the same as time passes. A flat monthly charge or a fee fixed for six months can keep adding to your payoff.
You need to know which arrangement you’re being offered—and what else could change the amount due.
What Is Flat-Fee Pre-Settlement Funding?
Under a fixed-total-fee arrangement, a funder provides an advance against your potential case recovery and agrees to a charge that doesn’t increase simply because repayment takes longer.
The fee may be stated as a dollar amount or calculated as a percentage of the advance. Once that calculation is fixed, you can see the advance and fee together as a payoff amount.
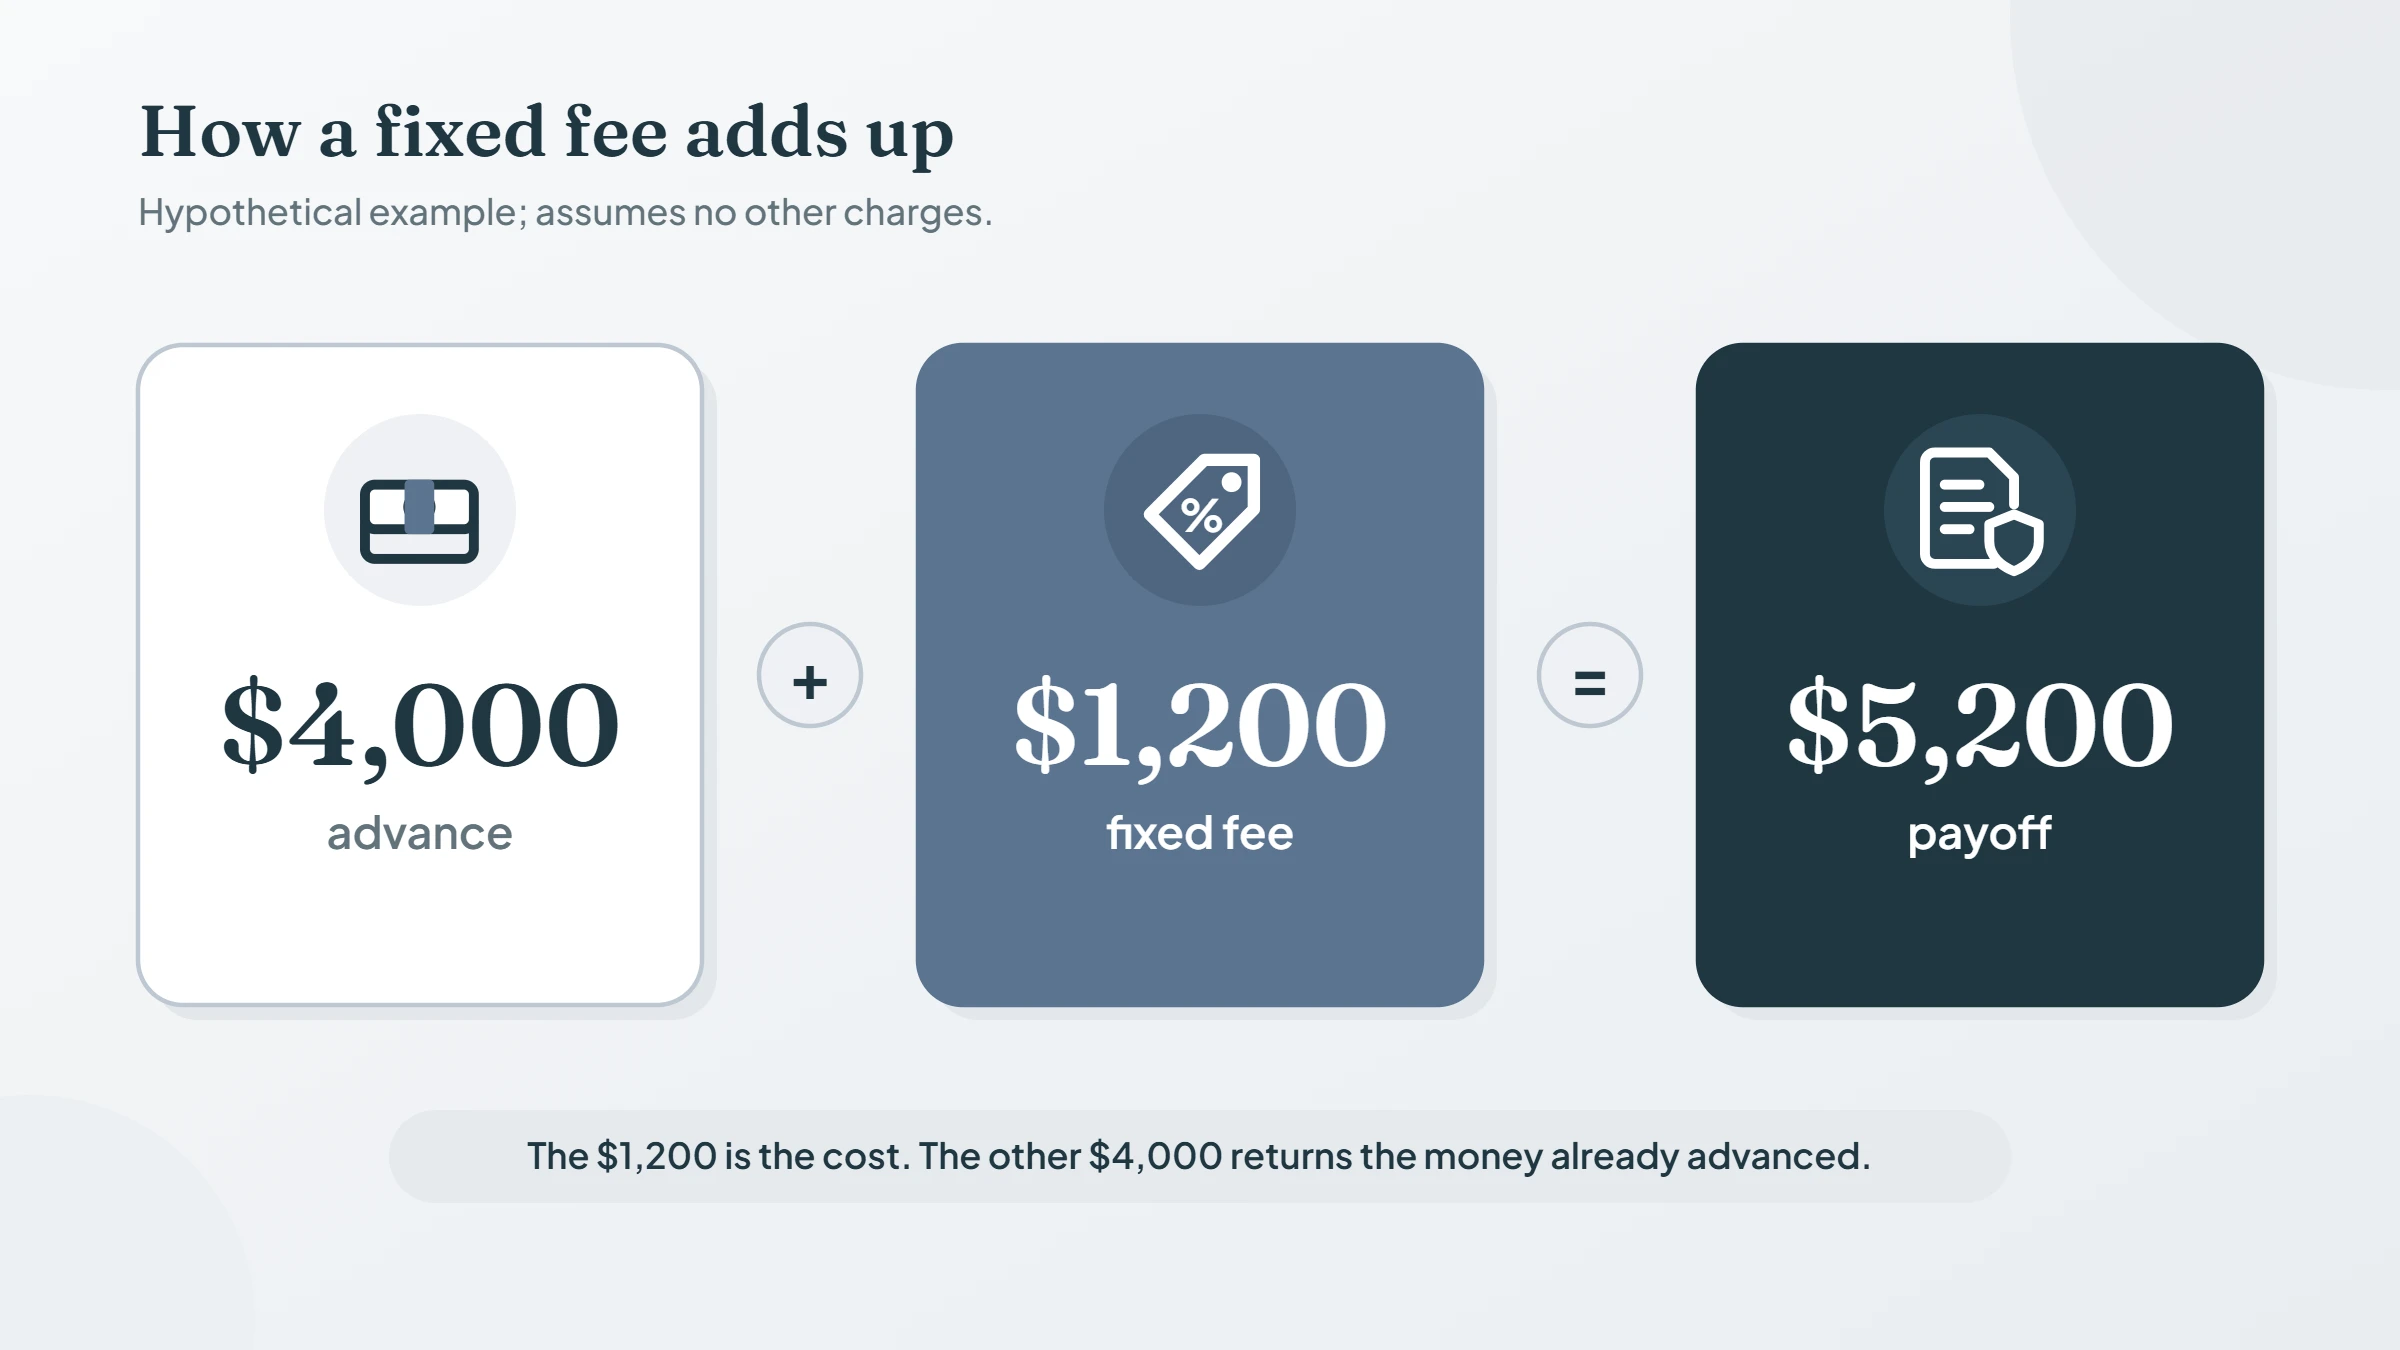
Suppose you receive $4,000 with a fixed $1,200 funding fee. The stated payoff is $5,200. The $1,200 is the cost; the other $4,000 returns the money already advanced.
That example assumes the fee covers the full period through repayment and no other charges apply. Read the agreement to confirm both points.
Does “Flat” Always Mean the Total Cost Stays Fixed?
No. The label gets used for different arrangements.
| Wording you might see | What to establish |
|---|---|
| One-time fixed fee | Does this cover the advance through repayment, and are there separate charges? |
| Flat monthly fee | The same charge may repeat each month. How long can it continue? |
| Non-compounding rate | Earlier interest doesn’t generate more interest, but charges can still accumulate over time. |
| Capped funding | Charges may increase until a limit is reached. What does that limit include? |
“No compounding” doesn’t mean “no increases.” A $100 monthly charge adds $600 over six months and $1,200 over twelve, even if the charge never increases.
Ask for the payoff at several dates. If the amount rises, find out why.
What Is the Percentage Applied To?
An offer described as “30% flat” still needs a base for that percentage.
Thirty percent of a $4,000 advance is $1,200. Thirty percent of a case recovery could be a very different amount.
Ask the funder to write out the calculation in dollars. State law matters here: California Business and Professions Code § 6253 prohibits determining the repayment amount for covered funding as a percentage of the claim recovery.
Is a Flat Fee Cheaper Than Monthly Charges?
Sometimes. The answer depends on the fee, the alternative offer, and when repayment happens.
A fixed fee can protect against increases caused by a longer wait. It can also cost more than time-based pricing when repayment happens quickly.
Here’s a hypothetical comparison using the same $4,000 advance:
| Time until repayment | $1,200 fixed fee | 2.5% simple monthly charge |
|---|---|---|
| Six months | $5,200 | $4,600 |
| Twelve months | $5,200 | $5,200 |
| Eighteen months | $5,200 | $5,800 |
The figures show total payoffs, including the advance. This is a math example, not a quote. It excludes additional fees, advances, and caps, and assumes enough case proceeds to cover repayment. Actual terms must meet applicable law.
Under these assumptions, monthly pricing costs less at six months. The offers match at twelve months. The fixed fee costs less at eighteen months.
Your case may take longer than expected. Compare several possible repayment dates with your attorney instead of choosing an offer around one predicted settlement date.
Does “No Interest” Mean There’s No Funding Cost?
No. A fee is still a cost, even when the offer doesn’t charge monthly interest.
Ohio Revised Code § 1357.01, for example, includes interest, administrative fees, origination fees, underwriting fees, and other fees in its definition of funding charges, regardless of what they’re called.
Look at the dollars you receive and the total amount payable. A “no interest” headline doesn’t answer either question on its own.
Also check when the fee is collected. Agreeing to a fee at signing and paying it out of pocket at signing are different things.
What Should Your Written Offer Explain?
Start with the cash available to you. Separate that amount from any money used to pay off previous funding, sent elsewhere on your behalf, or applied to fees.
Then check these details:
- The complete charge: Is the quoted fee the entire funding cost or one part of it?
- The period covered: Does it stay fixed through repayment or only until a specified date?
- Early repayment: Is the full fee still due, or can it be reduced?
- Cancellation rights: Check the deadline and required return procedure, separately from early-repayment terms.
- Other charges: Identify any permitted processing, delivery, late-payment, or other fees and when they apply.
- Repayment conditions: Check how the agreement handles no recovery, insufficient proceeds, and contract exceptions.
- Changes to the arrangement: Ask what happens if you request more funding or amend the agreement.
If the offer uses a percentage, ask for its dollar equivalent. If a term says “additional charges may apply,” ask which charges and how much.
What If You Need Another Advance?
A fixed fee on the first advance doesn’t automatically cover future funding.
A later request may need another case review and a new agreement. That agreement may carry another fee, subject to applicable law and the terms offered.
Ask for the combined payoff across all advances. Two individually fixed fees can still create a larger overall obligation.
Disclose existing funding before accepting another offer. Your attorney can help check the agreements and any state rules affecting additional funding.
How Is a Flat-Fee Advance Repaid?
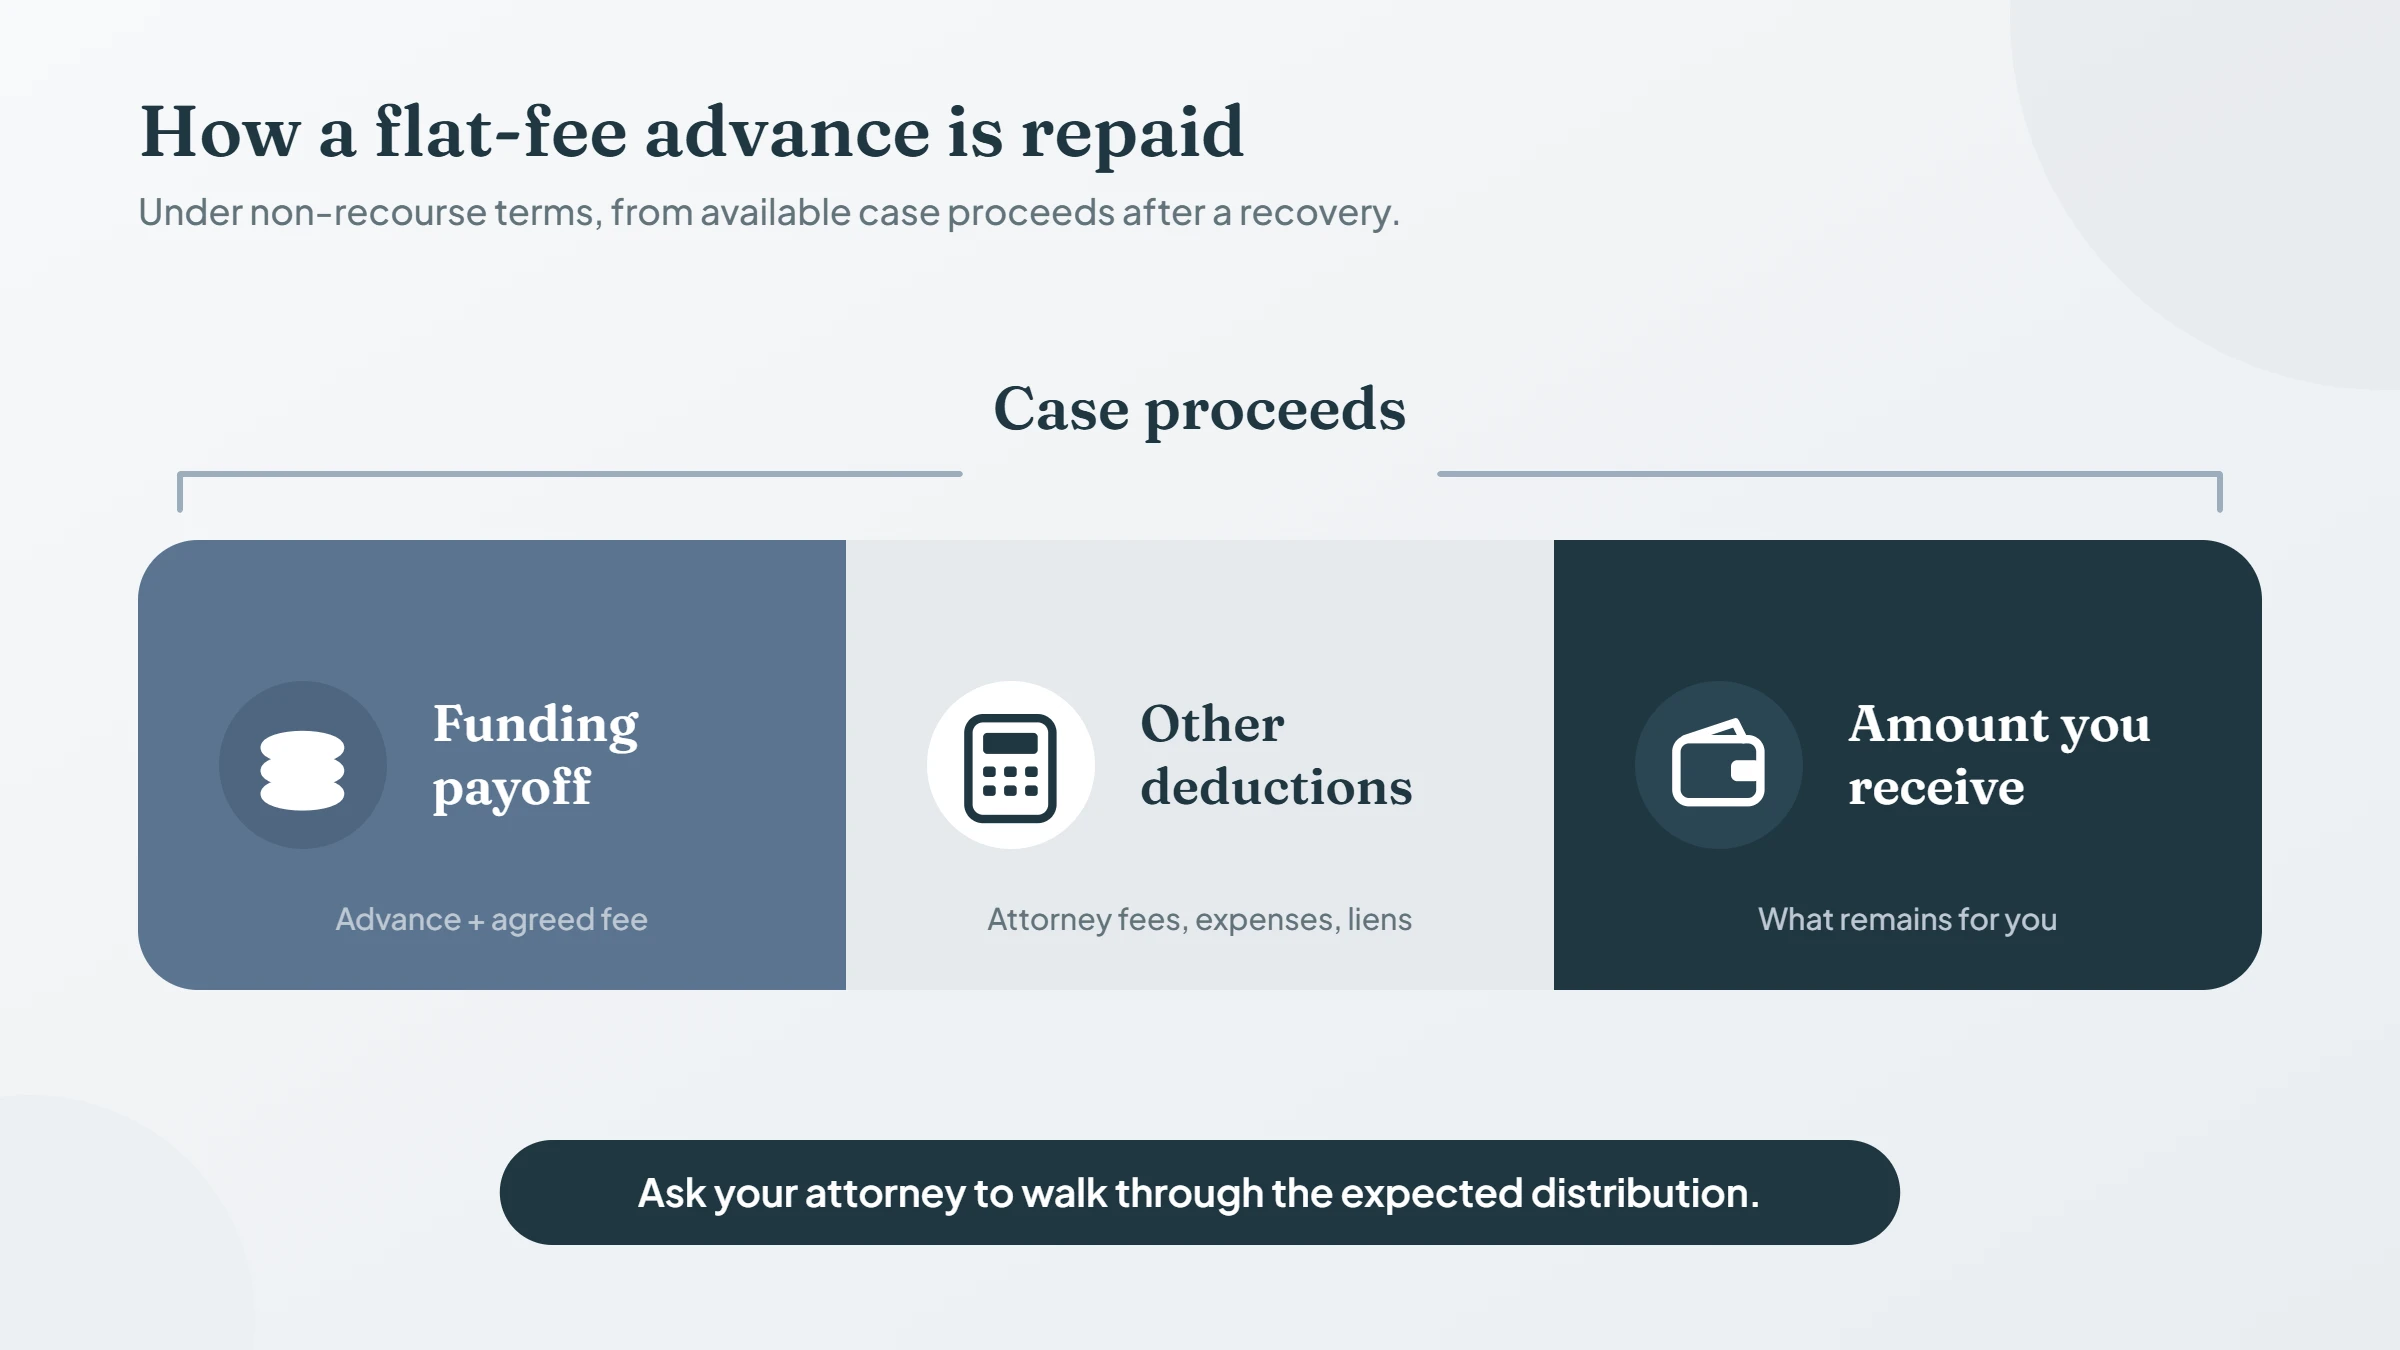
Under non-recourse terms, the advance and agreed charges generally come from available case proceeds after a successful recovery. Your attorney usually coordinates the funding payment when distributing those proceeds.
The funding deduction affects the money you receive at the end. Attorney fees, expenses, liens, and their payment priorities also matter.
Ask your attorney to walk through the expected distribution. Knowing the funding payoff is useful; knowing what may remain for you makes the decision easier to assess.
Compare Flat-Fee Funding Options Through MySettlement
MySettlement connects you with multiple pre-settlement funding offers, giving you options to compare before choosing.
Tell us how much you’re considering and that you’d like to explore flat-fee arrangements. Compare available offers for the cash provided, total charges, repayment terms, and any terms that could affect the payoff.
Approval and pricing depend on the participating funder, your case, and applicable law.
Frequently Asked Questions
Does a flat fee also mean the funding is non-recourse?
No. “Flat fee” describes pricing. “Non-recourse” describes repayment protection. Check both in the agreement. Under non-recourse terms, an ordinary unsuccessful claim producing no recovery generally means no repayment, subject to exceptions involving fraud, misrepresentation, or material breach.
Will the fee be lower if my case settles early?
Not automatically. Ask whether the fee is fully due regardless of timing, whether minimum charges apply, and whether the agreement or applicable law provides a reduction or refund.
Can I receive flat-fee funding in one lump sum?
A lump sum describes how the money is paid; a flat fee describes its price. They can be combined if the funder offers that arrangement for your claim. Confirm the payment method and pricing separately.