
- Structured Settlements
- What are Structured Settlements
- Best Structured Settlement Buyers
- How Selling Works
- Eligible Cases
- Eligibility Criteria
- Structured Settlement Regulations
- J&J Settlement
- Maui Wildfire Settlement
- Types of Structured Settlements
- Guaranteed Structured Settlements
- Increasing Structured Settlements
- Deferred Structured Settlements
- Life-Contingent Structured Settlements
- Future Lump Sum Settlements
- Annuities
- What Is An Annuity
- Guide to Selling an Annuity
- Income Annuities
- How Are Annuities Taxed?
- 7 Common Annuity Mistakes & How to Avoid Them
- Annuity Beneficiaries
- Types of Annuities
- Fixed Annuities
- Fixed Index Annuities
- Variable Annuities
- Immediate Annuities
- Deferred Annuities
- Registered Index-Linked Annuity
- Pre-Settlement Funding
- What is Pre-Settlement Funding
- How Pre-Settlement Funding Works
- Eligible Cases for Pre-Settlement Funding
- Pre-Settlement Funding Criteria
- Pre-Settlement Funding Regulations
- Types of Pre-Settlement Funding
- Non-Recourse Cash Advances
- Structured Pre-Settlement Funding
- One-Time Lump Sum Cash Advances
- Compounding Interest Funding
- Flat-Fee Structured Funding
- Structured Settlement Calculator



One specialist stays with you from your first call through funding.
November, 2026
You’ve spent years building your savings. Now you’re thinking about how to turn some of that money into an income you can count on.
An immediate annuity is one way to do that. You pay an insurance company a lump sum, and the company starts sending you regular payments soon afterward. Depending on the option you choose, those payments can last for a set number of years or for the rest of your life.
Sounds straightforward, right? The part that takes a little more thought is choosing what happens to those payments over time, especially if you need extra cash, prices rise, or you pass away.
Let’s walk through it.
How Does an Immediate Annuity Work?
An immediate annuity is an insurance contract that turns a premium into a series of income payments. The premium is usually a single lump sum, which is why you’ll often hear the term single premium immediate annuity, or SPIA.
Here’s the basic process:
- You pay an insurance company a lump sum.
- You choose how often you want payments and how long they should last.
- The insurer calculates your payment based on your choices and other details.
- Payments begin on the date stated in your contract.
Immediate annuity payments generally begin soon after purchase and are commonly described as starting within a year. Check the contract for your actual first payment date.
An immediate annuity is one of several types of annuities. Its defining feature is when income begins. The payment amount and duration depend on the contract you select.
Fixed vs. Variable Immediate Annuities
A fixed immediate annuity generally provides a stated payment amount. Some contracts offer scheduled increases, such as a payment that rises by a set percentage each year.
A variable immediate annuity has payments that can change based on investment performance and the contract’s formula. That means your income can rise or fall.
Here’s a detail worth checking: some variable contracts use an assumed investment return, or AIR, when calculating payments. If investment performance after charges falls below that benchmark, your next payment may decrease, even if the investments had a positive return.
How Long Do Immediate Annuity Payments Last?
That depends on the payment option you choose.
Some options pay income for life. Others pay for a fixed period. You can also choose certain options that provide payments to a spouse or beneficiary after your death.
| Payment option | How it works | What happens after death |
|---|---|---|
| Single life only | Pays income for one person’s lifetime | Payments generally end when that person dies |
| Joint and survivor | Covers two people and continues while either covered person is alive | The survivor receives the percentage selected in the contract |
| Period certain only | Pays for a set period, such as 10 years | A beneficiary generally receives any remaining payments in that period |
| Life with period certain | Pays for life, with a minimum payment period | A beneficiary receives remaining guaranteed payments if death occurs during that period |
| Life with cash refund | Pays for life and includes a refund feature | An eligible beneficiary receives any remaining amount calculated under the contract |
| Life with installment refund | Pays for life and includes a refund feature | Any remaining refund is paid in installments under the contract |
The New York Department of Financial Services describes these common options and how payments can continue after death.
What Does “Period Certain” Mean?
A period certain is a guaranteed payment period. A life annuity with a 10-year period certain, for example, pays for your lifetime and guarantees at least 10 years of payments.
Say payments begin and you pass away after four years. Your beneficiary would generally receive the remaining six years of guaranteed payments. If you live past the 10-year period, your lifetime payments continue.
That differs from a 10-year period-certain-only annuity, which ends after 10 years, even if you’re still alive.
What Is a Refund Feature?
A refund feature can provide a benefit if you die before receiving the amount specified in your contract. Depending on the option, the remaining amount may go to your beneficiary as a lump sum or through installments.
A refund feature protects a beneficiary. It does not automatically give you the right to withdraw your premium while you’re alive.
How Much Does an Immediate Annuity Pay?
There’s no single payment amount that applies to everyone. The insurer’s quote depends on the premium and the features you select.
There’s no single payment amount that applies to everyone. The insurer’s quote depends on the premium and the features you select.
Common factors include:
- The amount you pay as a premium
- Your age and, where permitted, sex
- The number of people covered
- The payment frequency and start date
- The payment period or lifetime option
- Survivor benefits and refund features
- Any scheduled increases or cash-access features
- The insurer’s pricing and current conditions
Some insurers also consider health in certain contracts. A person with a shorter life expectancy may qualify for a higher payment through a health-based underwriting option, though availability varies.
Payout Percentage vs. Investment Return
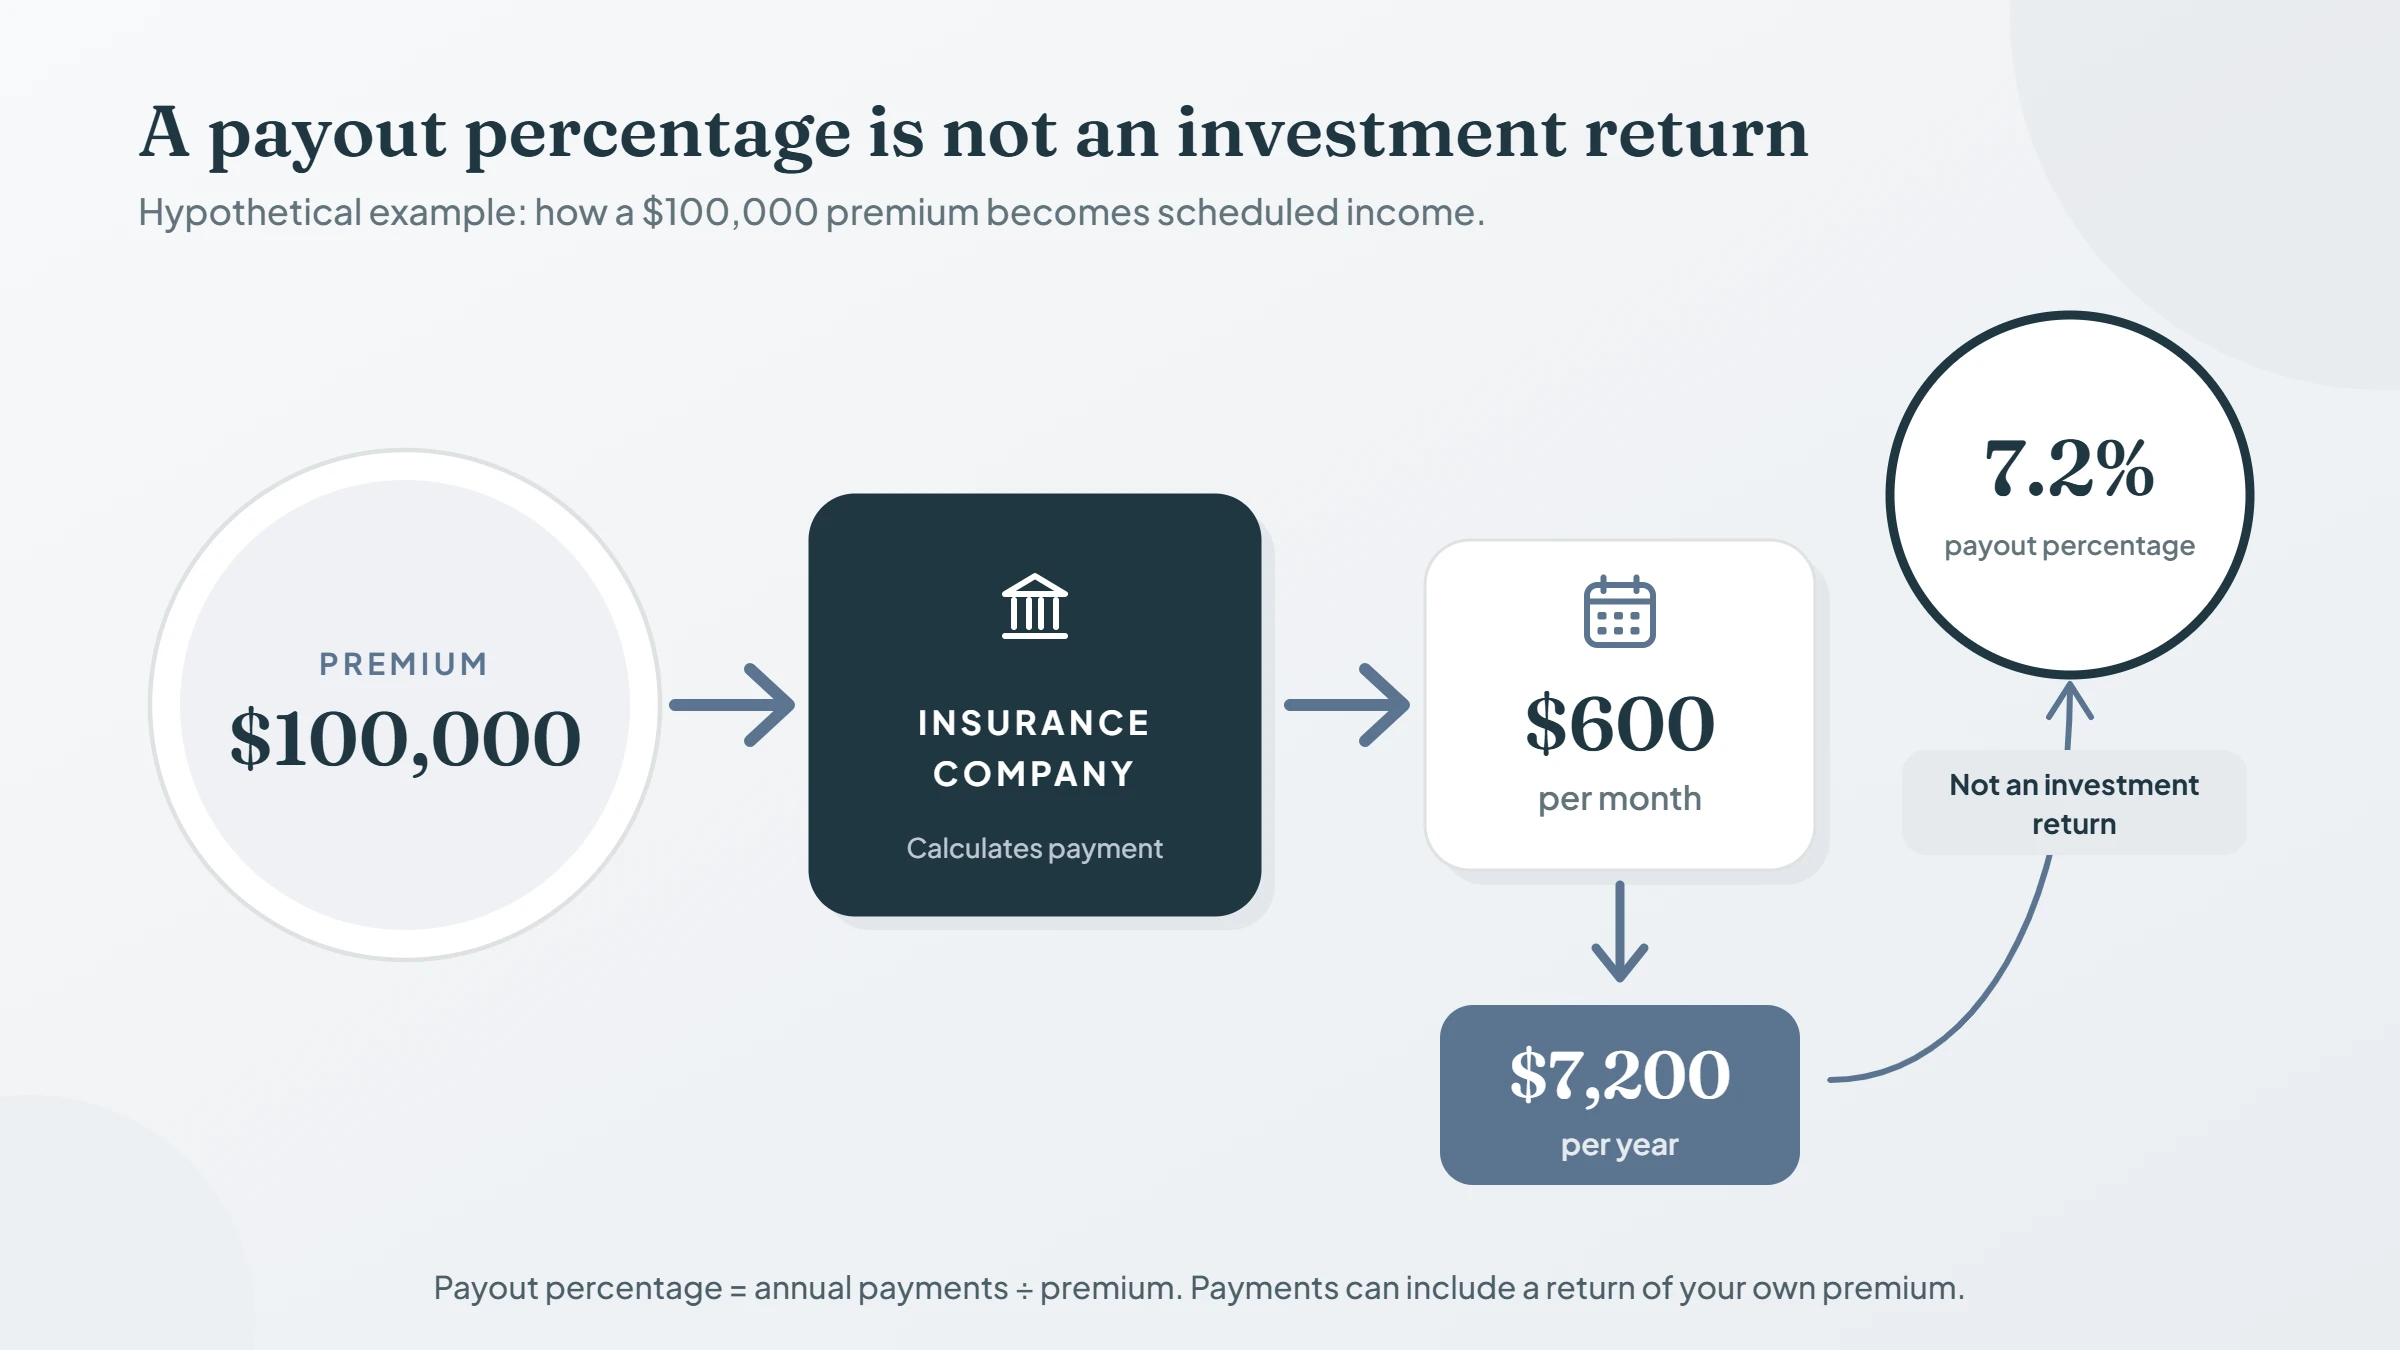
You may see an immediate annuity described as having a 7.2% payout rate. That can sound like a 7.2% investment return, but the two figures measure different things.
Here’s a hypothetical example:
- Premium: $100,000
- Monthly payment: $600
- Annual payments: $7,200
- Annual payout percentage: 7.2%
The payout percentage is the annual payment divided by the premium. The payments can include a return of the money you paid into the annuity, along with other amounts supporting the insurer’s obligations.
How much you receive over time depends on the payment option and, for a lifetime annuity, how long payments continue.
| Time receiving payments | Total received at $600 per month |
|---|---|
| 5 years | $36,000 |
| 10 years | $72,000 |
| 15 years | $108,000 |
| 20 years | $144,000 |
These figures are a teaching example, not a quote. They exclude taxes, inflation, beneficiary payments, and the time value of money.
How Much Would $100,000 Pay Per Month?
A $100,000 premium could produce different monthly payments depending on your age, insurer, payment option, and other contract features.
A life-only quote will generally differ from a quote that includes survivor income or a refund benefit. When comparing offers, use the same assumptions so you can see what each contract provides for the same premium.
Why Do People Buy Immediate Annuities?
The biggest reason is often predictable income. A lifetime option can help cover recurring expenses for as long as the covered person lives, subject to the insurer’s ability to pay.
Let’s say your essential expenses are $4,200 a month, and you already receive $3,000 in dependable monthly income after tax. You have a $1,200 monthly gap to consider.
An immediate annuity may help cover part of that gap. You would still need to account for taxes, future price increases, cash reserves, and the income your household might need after a death.
Protection Against Outliving Your Income
A lifetime annuity uses a concept called longevity pooling. The insurer combines the risks of many annuity owners: some receive payments for a shorter time, while others receive them for longer.
That pooling helps support income for people who live longer than expected. It also means someone who dies early under a life-only option may receive considerably less than the premium paid.
A Simpler Income Schedule
Regular payments can make budgeting easier. You know when income is scheduled to arrive and can plan expenses around it.
The tradeoff is that money committed to an immediate annuity may be difficult to access later. That deserves just as much attention as the payment amount.
What Are the Risks of an Immediate Annuity?
A dependable payment can be useful, but it is only one part of a financial plan. Here are the tradeoffs to consider before committing a large sum.
Inflation Can Reduce Buying Power
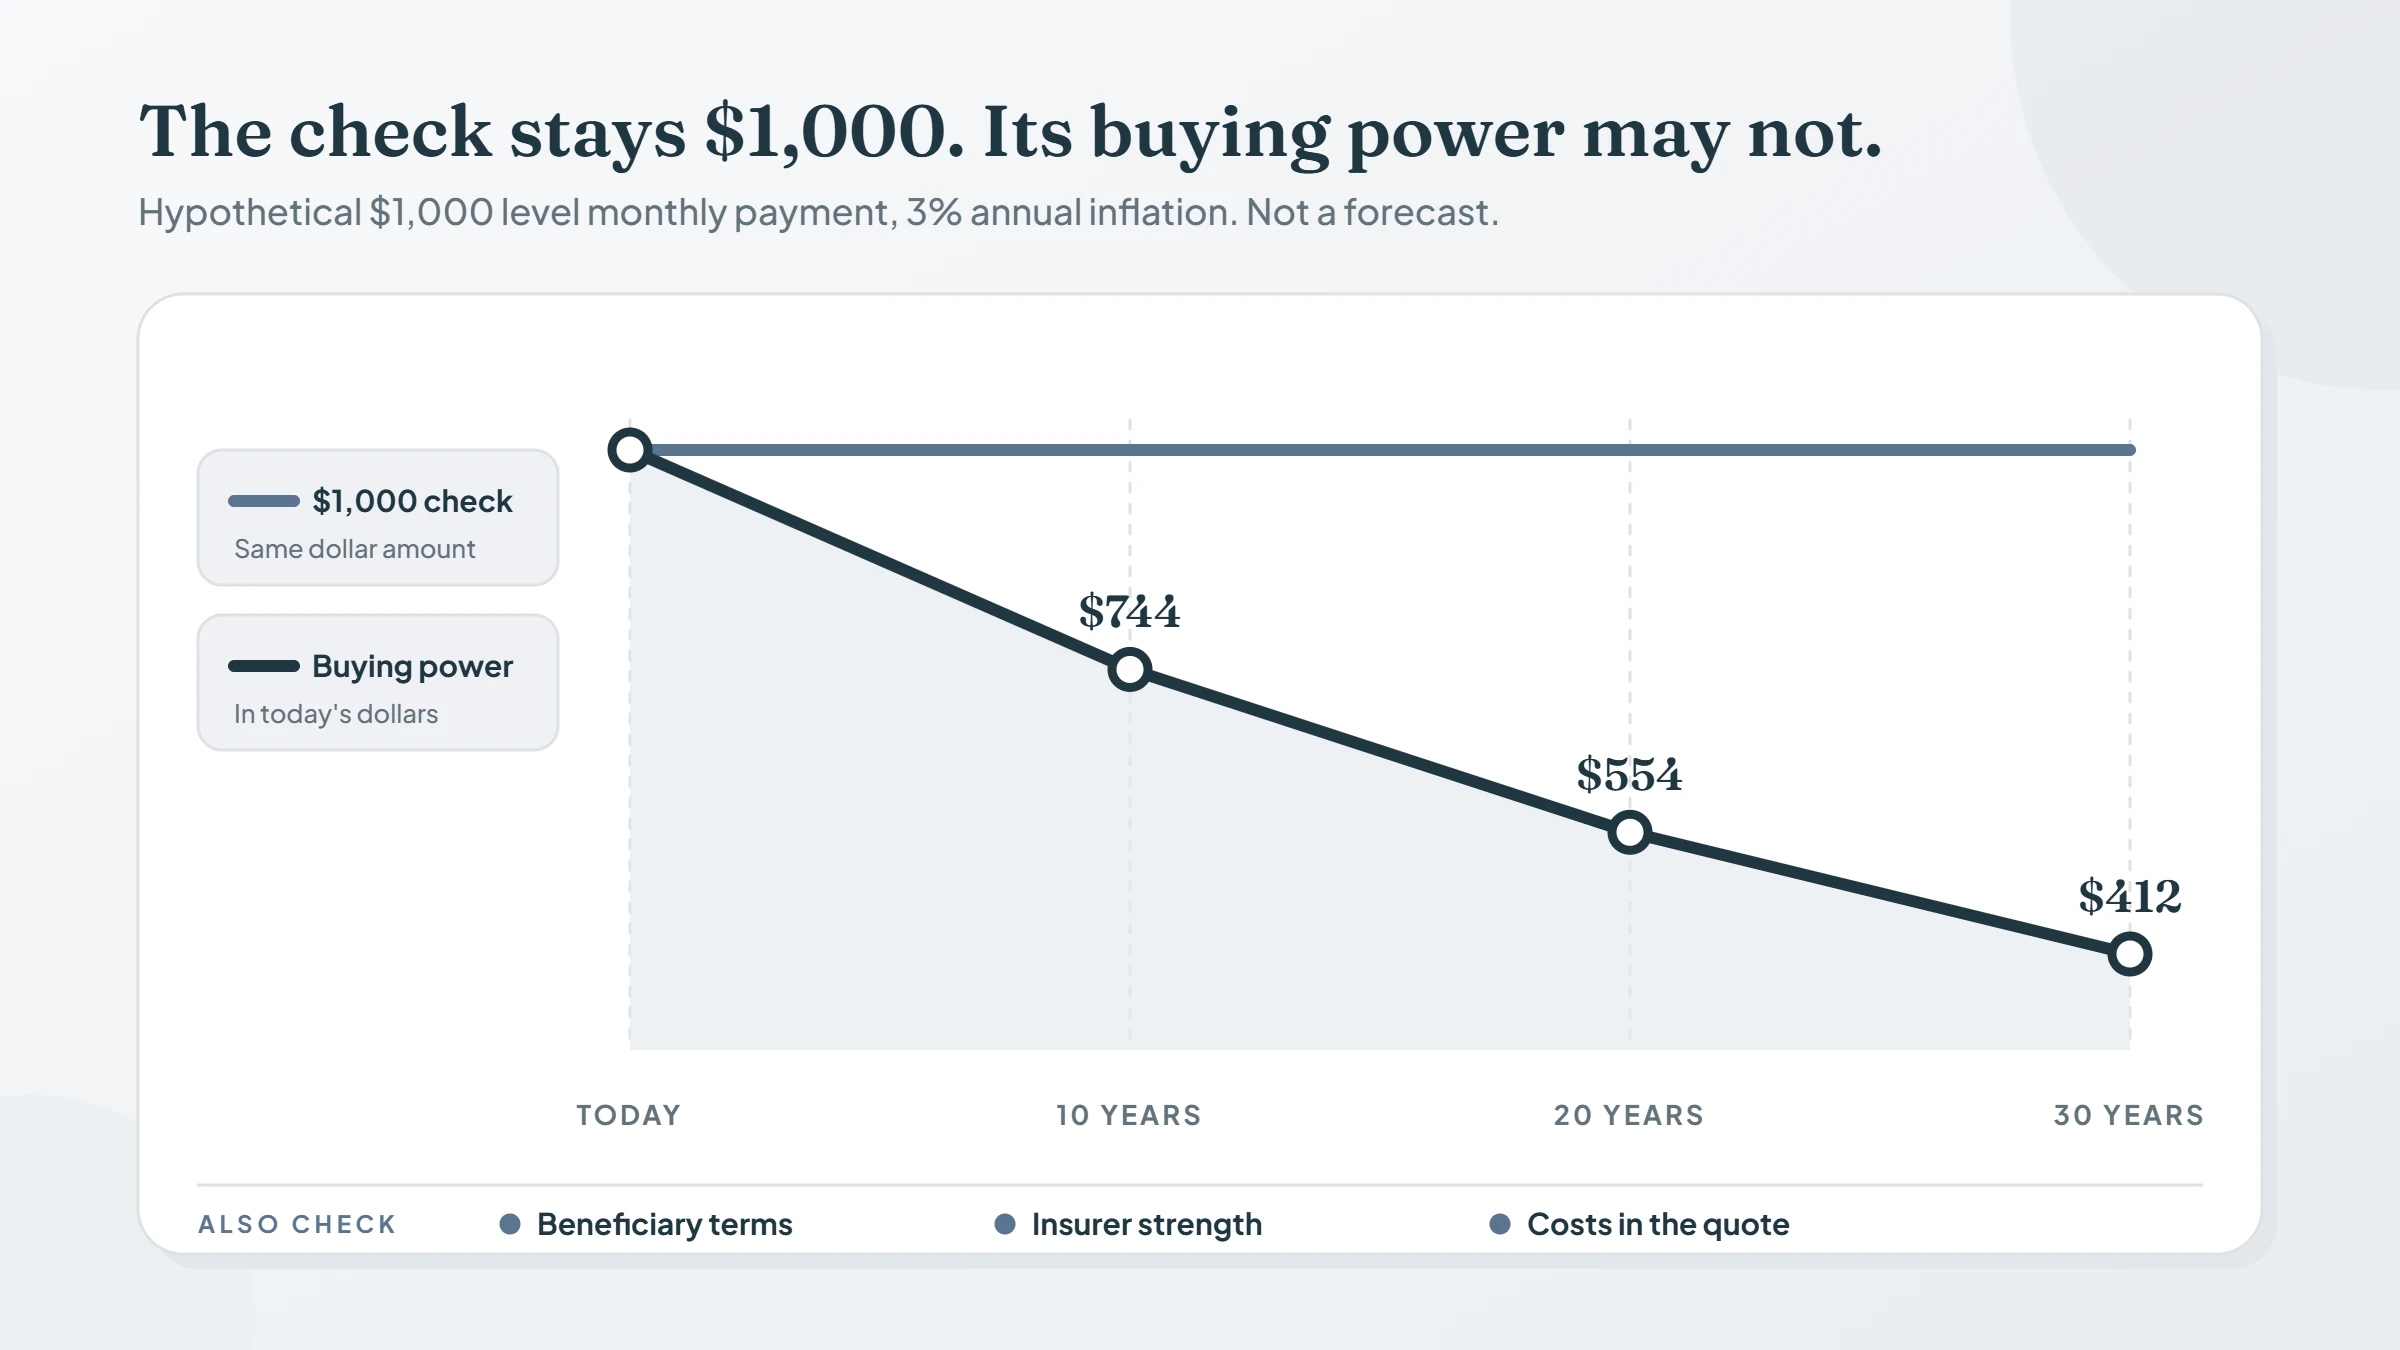
A level payment stays the same in dollars, but prices may rise. That means the payment could buy less over time.
The following example assumes a $1,000 monthly payment and constant 3% annual inflation. It shows buying power in today’s dollars, not a forecast of future inflation.
| Years later | Approximate buying power |
|---|---|
| Starting point | $1,000 |
| 10 years | $744 |
| 20 years | $554 |
| 30 years | $412 |
Some contracts offer scheduled increases. A 3% annual increase can help, but it will not necessarily match actual inflation. A contract tied to a consumer price index may use a different formula, so check its terms, limits, and starting payment.
Early Death Can Reduce Total Payments
A life-only annuity generally stops when the covered person dies. If that happens soon after payments begin, the total received could be much less than the premium.
A period certain or refund feature can provide beneficiary protection, but that protection generally affects the starting payment. Compare the income and the protection together.
The Insurer Must Be Able to Pay
An annuity guarantee depends on the issuing insurance company’s ability to meet its obligations. Check the financial strength of the issuing insurer, which may have a different name from the company selling the contract.
Annuities are insurance contracts, so FDIC deposit insurance does not cover them. State insurance protections have their own eligibility rules and limits.
Costs Affect the Payment You Receive
A fixed immediate annuity may not show a separate annual fee in the same way an investment account does. That does not mean the arrangement has no costs.
The insurer’s expenses, compensation, pricing, and the features you choose can affect the payment offered. Ask about separately charged fees and how the person recommending the annuity is paid.
Can You Access Money After Buying?
Immediate annuities generally have limited cash access, but the options depend on the contract. Four terms are useful to know.
1. Free-Look Cancellation
A free-look period gives you a limited time to review a new contract and request cancellation. The deadline and refund calculation depend on applicable rules and the contract.
Ask when the review period begins, how to cancel, and what amount would be returned.
2. Payment Acceleration
Some contracts allow you to receive certain future payments early. Depending on the terms, later payments may pause or change to account for the advance.
This feature brings payments forward. It is different from withdrawing an account balance.
3. Commutation
A commutation provision may let you exchange some future payments for a lump sum. Your later income can decrease or end, depending on the arrangement.
Availability can depend on the contract, the payment option, and other restrictions. Ask how the lump sum is calculated and what income would remain afterward.
4. Sale of Payment Rights
In some circumstances, a person may be able to sell eligible future payment rights to a third party. The contract, ownership arrangement, applicable law, and proposed transaction all matter.
A sale can also have tax consequences and reduce future income. The presence of a commutation feature does not automatically establish that payment rights can be sold.
How Are Immediate Annuities Taxed?
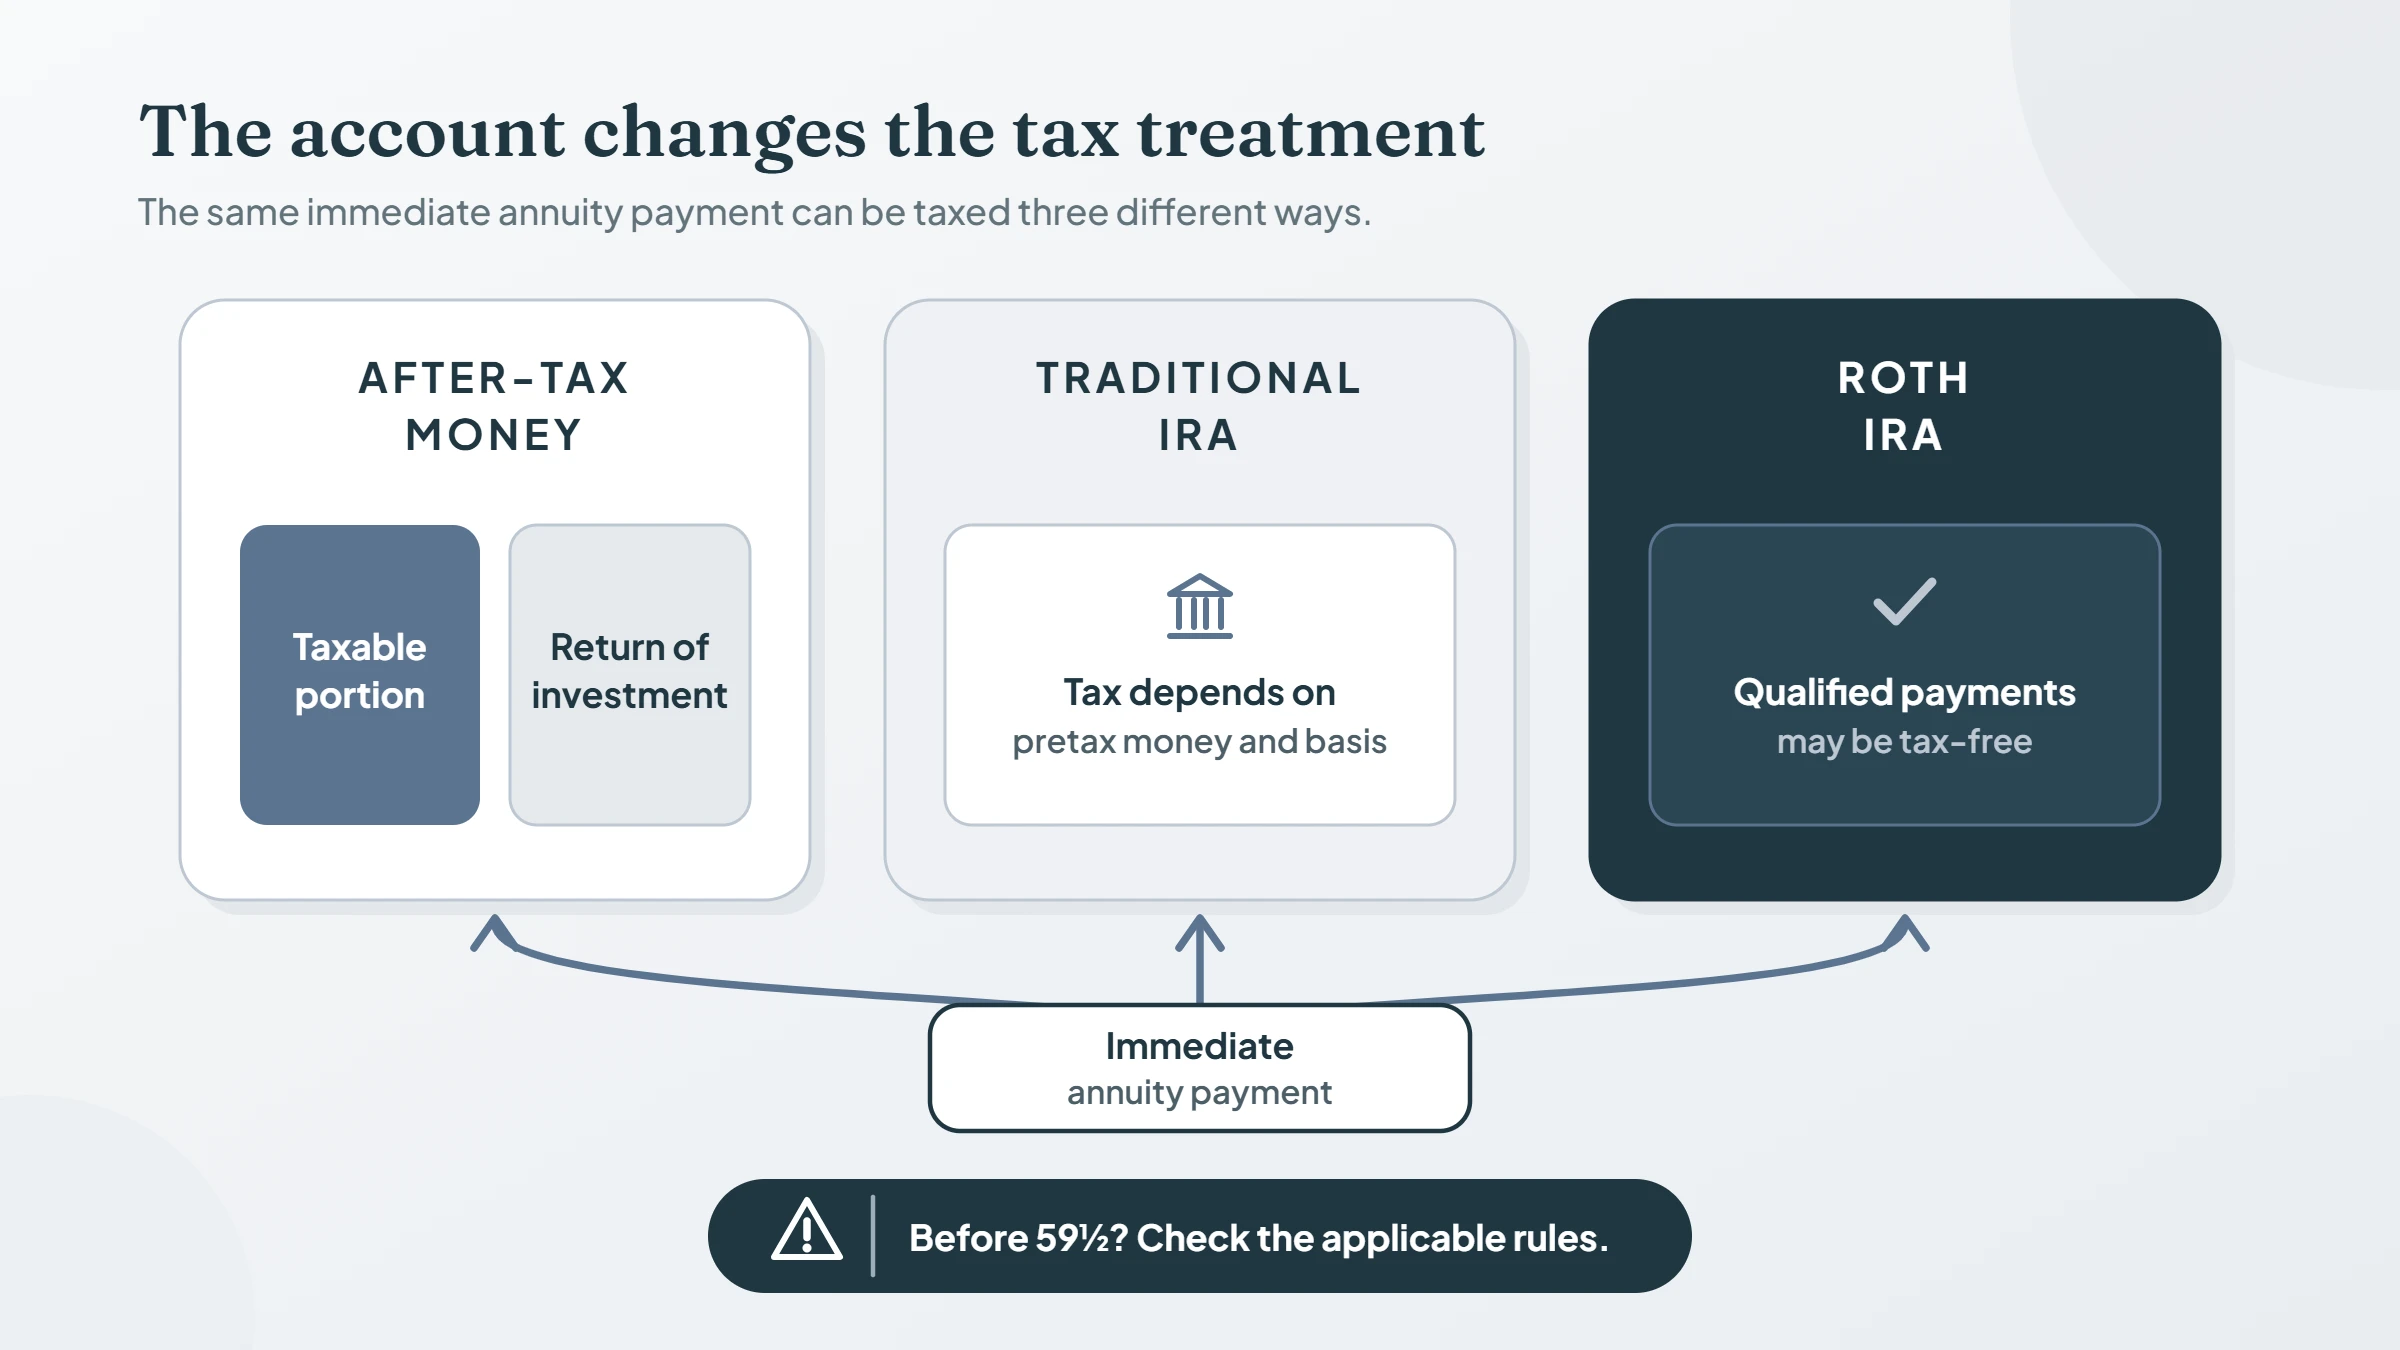
The tax treatment depends partly on where the premium came from and how the annuity is owned.
Annuity Bought With After-Tax Money
A personally owned annuity purchased outside a retirement account is generally called a nonqualified annuity.
When the contract is annuitized, each payment generally includes a taxable portion and a portion treated as a return of your investment. The IRS uses an exclusion calculation to determine the amounts.
Once the recoverable investment has been fully returned under the applicable rules, later payments can become fully taxable. Refund features and variable payments can affect the calculation. IRS Publication 939 explains the general rule and its different calculations.
Annuity Held in a Traditional IRA
If an immediate annuity is held in a traditional IRA, payments are generally taxable to the extent they come from untaxed contributions and earnings. After-tax basis in the IRA can change the taxable amount.
Annuity Held in a Roth IRA
Qualified Roth IRA distributions can be tax-free. The account and distribution requirements still apply.
Taking money out of a Roth IRA and using it to buy an annuity outside the IRA is a separate transaction. The new outside contract does not automatically keep Roth treatment.
What About the 10% Additional Tax?
Some taxable distributions before age 59½ may face an additional federal tax, but the rules depend on the funding arrangement.
Federal law provides a specific exception for distributions under a qualifying nonqualified immediate annuity contract. IRA and employer-plan distributions follow separate rules, so the word “immediate” alone does not settle the question.
An exchange from an older deferred annuity also needs care. IRS Publication 575 explains that the original contract’s purchase date can matter when assessing the immediate-annuity exception. Regular income tax is a separate issue.
RMDs and Other Income Effects
If you use part of an IRA to purchase an annuity, special rules may apply to your required minimum distribution, or RMD. The IRS describes an election that can combine the annuity value with the remaining account balance for the calculation. Ask your provider or tax professional how the rule applies to your arrangement.
Taxable annuity income may also affect the tax on Social Security benefits or income-related Medicare premiums. Those effects depend on your total income and circumstances.
Immediate Annuity vs. Deferred Annuity
The main difference is when income is scheduled to begin.
An immediate annuity starts income soon after purchase. A deferred annuity delays income until a later date. Some deferred annuities are designed to accumulate value before the owner chooses an income option.
| Feature | Immediate annuity | Deferred annuity |
|---|---|---|
| Income begins | Soon after purchase, according to the contract | At a later date |
| Typical purpose | Turn money into income now or soon | Build value or arrange income for the future |
| Premiums | Usually one lump sum | May allow one or multiple premiums, depending on the contract |
| Cash access | Often limited after purchase | Depends on contract terms, including any surrender charges |
Is an Immediate Annuity Right for You?
Start by looking at the job you need the money to do.
A lifetime immediate annuity may be worth considering if you want income to help cover ongoing expenses and have enough money elsewhere for emergencies. A person who expects to need a large portion of their savings soon may place a higher value on access to cash.
Before you buy, ask:
- How much income do I need after tax?
- Do I have enough accessible savings for emergencies and future expenses?
- Should payments continue for a spouse or beneficiary?
- What happens if I die before the first payment or early in the contract?
- Can payments increase, decrease, or remain level?
- Which parts of the quote are guaranteed?
- Can I access extra cash later, and what happens to future payments?
- What fees or compensation affect the recommendation?
- How would the purchase affect my taxes, Social Security benefits, or Medicare premiums?
- What income would my existing annuity provide if I used its current payout option?
That last question matters if you already own a deferred annuity. A new SPIA is not automatically the better deal. Compare the income, survivor benefits, surrender costs, and features you might give up.
New York’s financial regulator specifically discusses comparing an existing annuity’s income option when a replacement is recommended.
What If You Need a Lump Sum Later?
Life can change after you start receiving annuity payments. A major expense may come up, or your monthly income needs may shift.
If your contract permits it and your payment rights qualify, selling some future payments may be an option. MySettlement purchases eligible annuity payment rights and can review your situation to see if a sale is possible.
Before making a decision, compare the cash you would receive after applicable costs and taxes against the future income you would give up. You can learn more on our annuity payments page.
Frequently Asked Questions
Is an immediate annuity always paid for life?
No. You can choose a lifetime option or, where available, payments for a fixed period. A fixed-period annuity ends when that period ends.
Can immediate annuity payments increase?
Yes. Some fixed contracts offer scheduled increases, and some variable payments change according to an investment-based formula. The details depend on the contract.
Can I get my premium back?
Some contracts offer cancellation during a free-look period, and others may provide a commutation or acceleration feature. Many immediate annuities have limited access to cash after purchase, so review the contract before committing your money.
Is there a minimum amount to buy an immediate annuity?
Minimum premiums depend on the insurer and product. Ask for the minimum on the specific contract you’re considering.
What happens to an immediate annuity when I die?
It depends on the option you selected. Life-only payments generally stop at death, while a survivor, period-certain, or refund feature may provide payments to another person under the contract.