
- Structured Settlements
- What are Structured Settlements
- Best Structured Settlement Buyers
- How Selling Works
- Eligible Cases
- Eligibility Criteria
- Structured Settlement Regulations
- J&J Settlement
- Maui Wildfire Settlement
- Types of Structured Settlements
- Guaranteed Structured Settlements
- Increasing Structured Settlements
- Deferred Structured Settlements
- Life-Contingent Structured Settlements
- Future Lump Sum Settlements
- Annuities
- What Is An Annuity
- Guide to Selling an Annuity
- Income Annuities
- How Are Annuities Taxed?
- 7 Common Annuity Mistakes & How to Avoid Them
- Annuity Beneficiaries
- Types of Annuities
- Fixed Annuities
- Fixed Index Annuities
- Variable Annuities
- Immediate Annuities
- Deferred Annuities
- Registered Index-Linked Annuity
- Pre-Settlement Funding
- What is Pre-Settlement Funding
- How Pre-Settlement Funding Works
- Eligible Cases for Pre-Settlement Funding
- Pre-Settlement Funding Criteria
- Pre-Settlement Funding Regulations
- Types of Pre-Settlement Funding
- Non-Recourse Cash Advances
- Structured Pre-Settlement Funding
- One-Time Lump Sum Cash Advances
- Compounding Interest Funding
- Flat-Fee Structured Funding
- Structured Settlement Calculator



One specialist stays with you from your first call through funding.
November, 2026
Your annuity may provide income for years, but your financial needs can change. A medical expense, home repair, or other major cost might require more than your next scheduled payment.
Selling eligible annuity payments can give you a lump sum today in exchange for some or all of those future payments. The buyer purchases them at a discount, so you receive less than their combined scheduled amount.
Before accepting an offer, you need to know which payments can be sold, what you would receive, and what income you would keep. This guide walks you through those decisions.
What Does Selling an Annuity Mean?
Selling annuity payments generally means transferring the right to receive specified future payments to a buyer. The buyer pays you an agreed lump sum and receives the payments included in the sale.
Depending on your arrangement, you may be able to:
- Sell all remaining eligible payments included in the transaction.
- Sell selected payments and retain the others.
A partial sale also pays you a lump sum. You do not necessarily have to give up your entire payment stream to access cash.
The available options depend on your contract, payment rights, buyer, and applicable requirements.
Can Every Annuity Be Sold?
No. The word annuity covers different arrangements, and the product’s name alone does not determine whether you can sell it.
| Your arrangement | What needs to be checked |
|---|---|
| Privately purchased annuity | Ownership, transfer restrictions, payment terms, and insurer requirements. |
| Structured settlement annuity | The settlement payment rights and applicable legal approval process. |
| Inherited annuity | Beneficiary rights, payout arrangements, contract restrictions, and tax treatment. |
| IRA or retirement-plan annuity | Retirement-account restrictions and permitted distribution or transfer options. |
IRA annuities should not be treated like ordinary payment rights available for purchase. Federal law requires individual retirement annuities under § 408(b) to be nontransferable by the owner.
A payment schedule also matters. An annuity still accumulating value can present different options from one already providing income. Ask the insurer and buyer to review your actual documents before assuming a sale is available.
Selling vs. Withdrawing or Surrendering
These options can all involve receiving cash, but they are different transactions.
| Option | What happens |
|---|---|
| Selling payments | A third-party buyer pays you for eligible future payment rights. |
| Making a withdrawal | Your insurer pays out part of an accessible contract value. |
| Surrendering the contract | You receive the available surrender value and terminate the contract. |
Many deferred annuities allow withdrawals during the accumulation phase. Surrendering or withdrawing may trigger charges, adjustments, taxes, or changes to benefits. An annuity that has been converted into income payments may offer fewer withdrawal options.
Ask your insurer for the options available under your contract. Then compare those figures with a purchase offer, including costs and tax consequences.
How to Sell Annuity Payments in 5 Steps
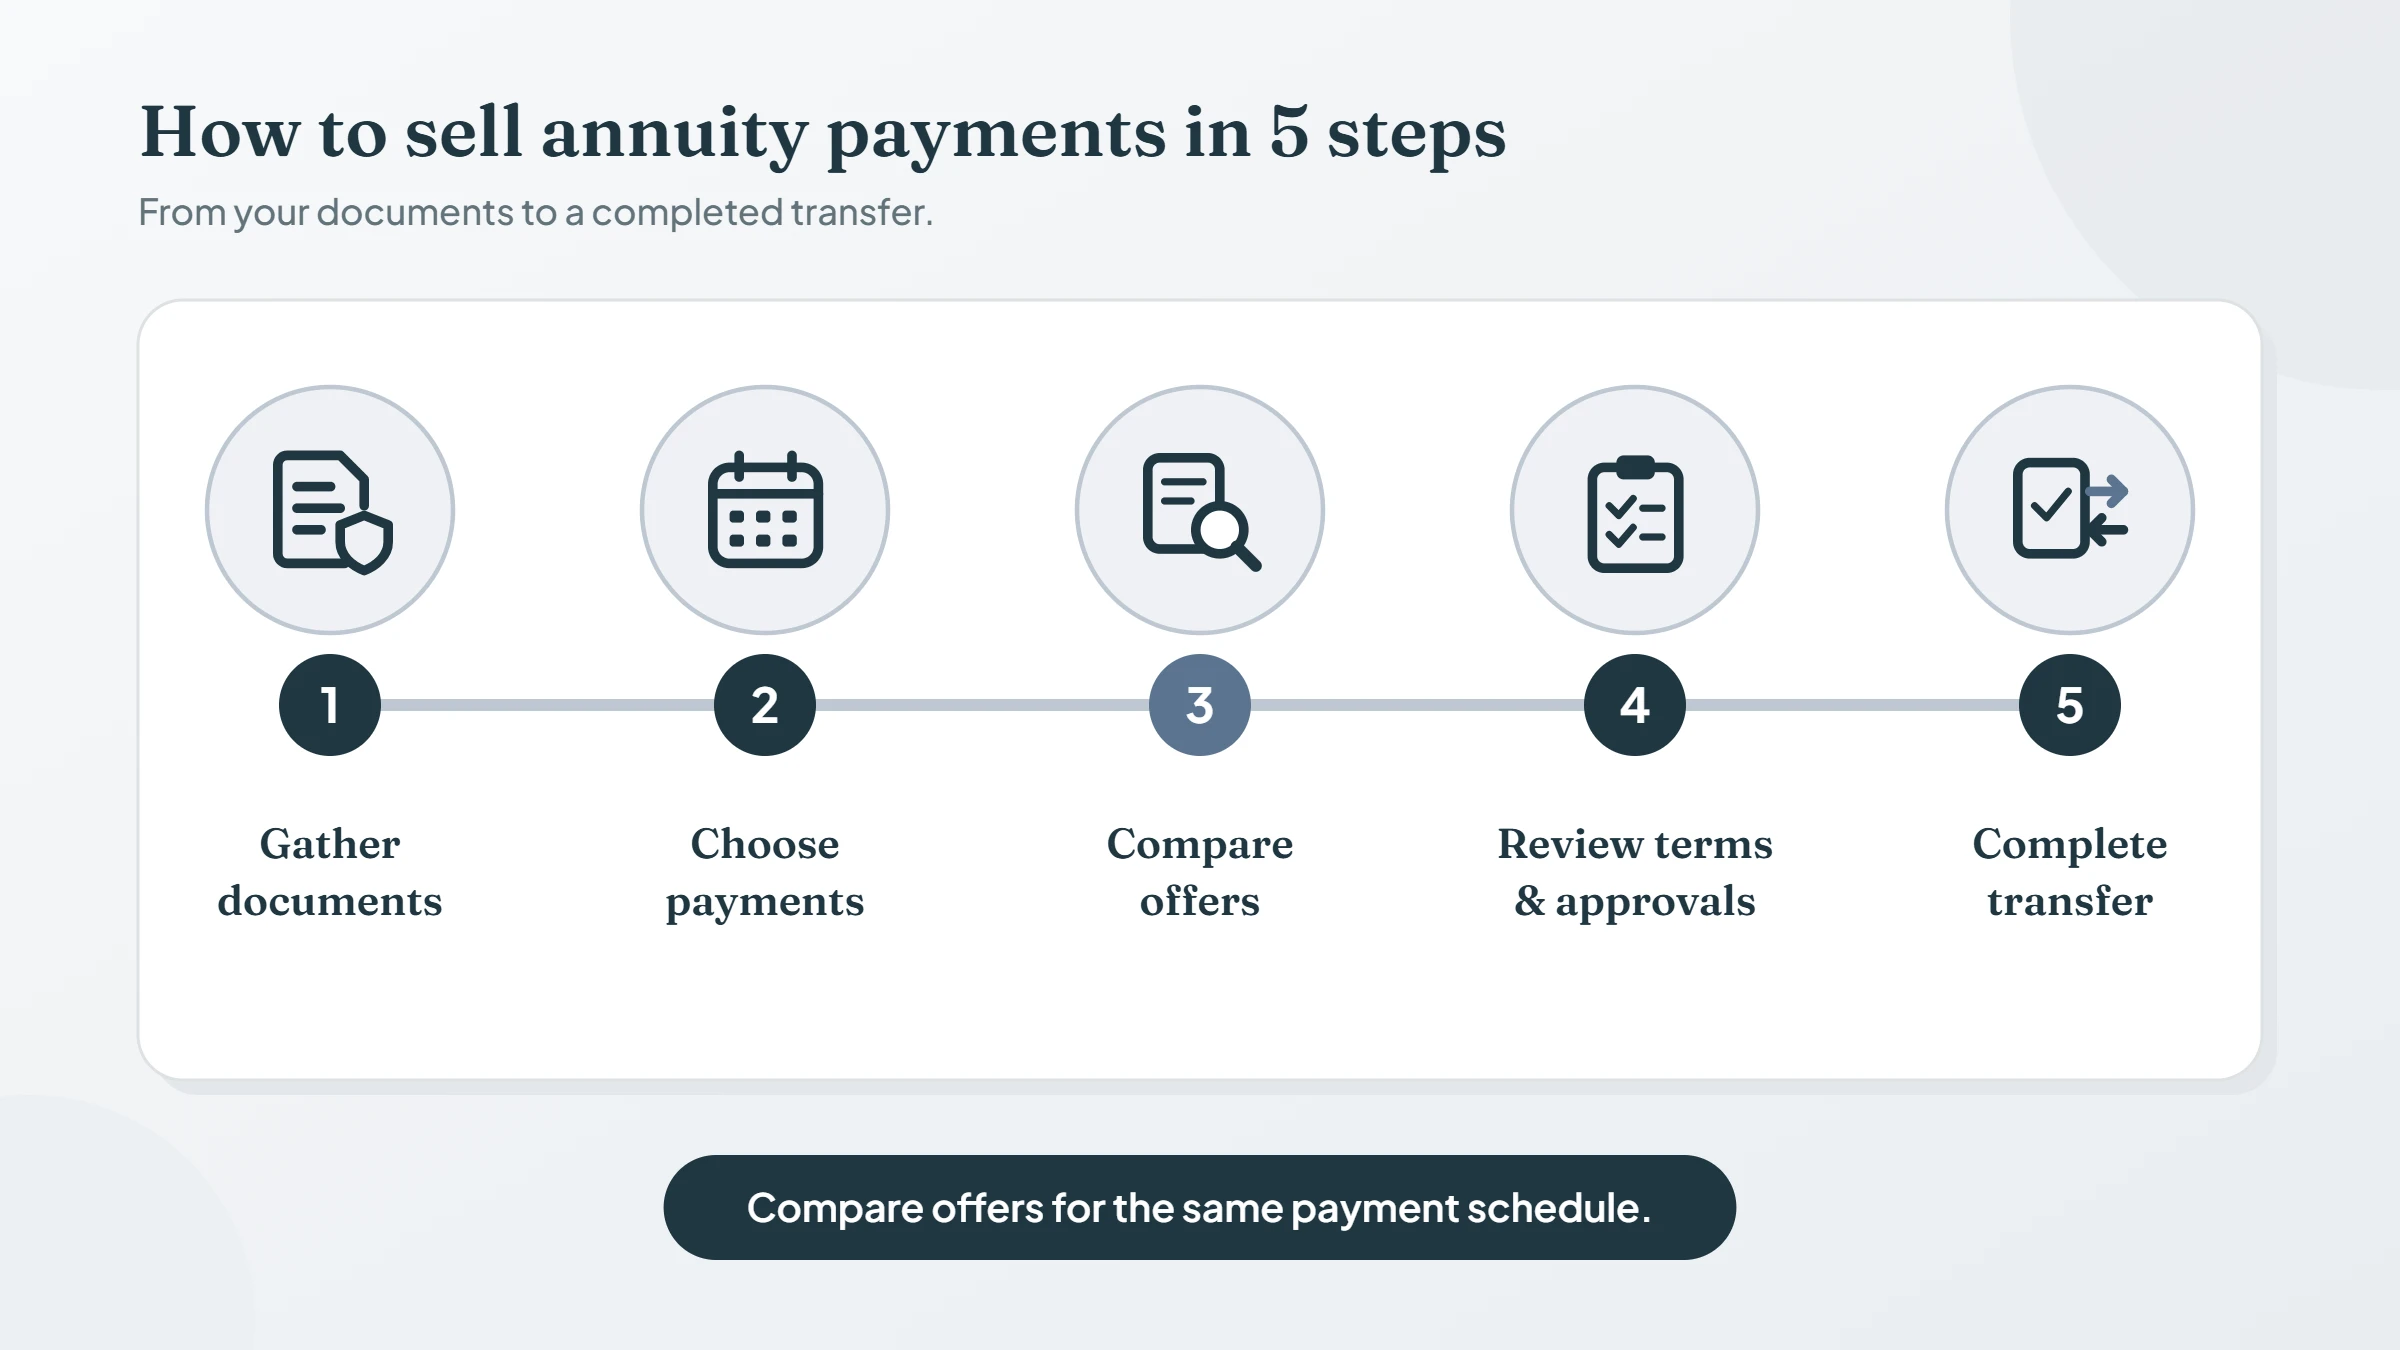
Step 1: Gather Your Annuity Documents
Start with your contract and any amendments. A buyer needs to establish what payment rights you hold and whether they can be transferred.
Useful documents may include:
- Your annuity contract and payment schedule.
- A recent statement or payment confirmation.
- Identification and ownership information.
- Details of previous assignments or payment sales.
- Beneficiary documents, if the annuity was inherited.
- Settlement documents, if the payments come from a legal settlement.
The buyer may request additional information. An owner, annuitant, and beneficiary can have different roles, so receiving payments does not always mean you own the underlying contract.
Step 2: Decide Which Payments to Discuss
Think about the amount you need and the income you rely on.
A partial sale may allow you to address an expense while retaining other scheduled payments. However, not every contract or transaction permits every partial-sale structure.
Ask for a clear explanation of:
- Which payments would be transferred.
- Which payments would remain yours.
- When your retained payments would arrive.
- Whether any payments depend on someone remaining alive.
Selling a particular payment period is not necessarily the same as splitting each monthly payment.
Step 3: Request and Compare Written Offers
A useful offer identifies the payments being purchased, the purchase price, applicable expenses, and the net amount you would receive.
Compare offers for the same payment schedule. A larger offer may involve giving up more payments, so the highest headline number is not automatically the best comparison.
Ask how long the quote remains valid and what could change it. Review the proposal with an independent financial or legal professional before committing.
Step 4: Review the Agreement and Required Approvals
Read the purchase agreement carefully. Check the payment rights being transferred, costs, conditions, cancellation provisions, and requirements for completion.
Covered structured settlement transfers generally require court approval under applicable state law. A privately purchased annuity may follow a different process involving contract and insurer requirements.
The buyer should explain which approvals apply to your arrangement. Approval is not guaranteed, and a promised timeline should account for document collection, insurer processing, and any required legal proceedings.
Step 5: Complete the Transfer and Receive Your Lump Sum
Once the necessary requirements are satisfied and the transaction closes, the buyer pays the agreed lump sum.
Confirm the payment method and expected delivery timing. Keep copies of the completed agreement, approval documents, and final breakdown.
You give up the rights to the payments included in the completed sale. Make sure you understand that consequence before closing.
How Much Will You Receive?
An offer depends on the payments being purchased and their value today.
Factors may include:
- Payment amounts and dates.
- The number of payments transferred.
- Guaranteed periods or survival conditions.
- The insurer responsible for payment.
- The discount rate and transaction costs.
Here’s a simple illustration. Payments of $1,000 per month for ten years total $120,000. A hypothetical $90,000 offer would provide cash now in exchange for that future schedule.
What About Taxes and Other Costs?
The buyer’s discount, insurer charges, transaction expenses, and taxes are separate considerations.
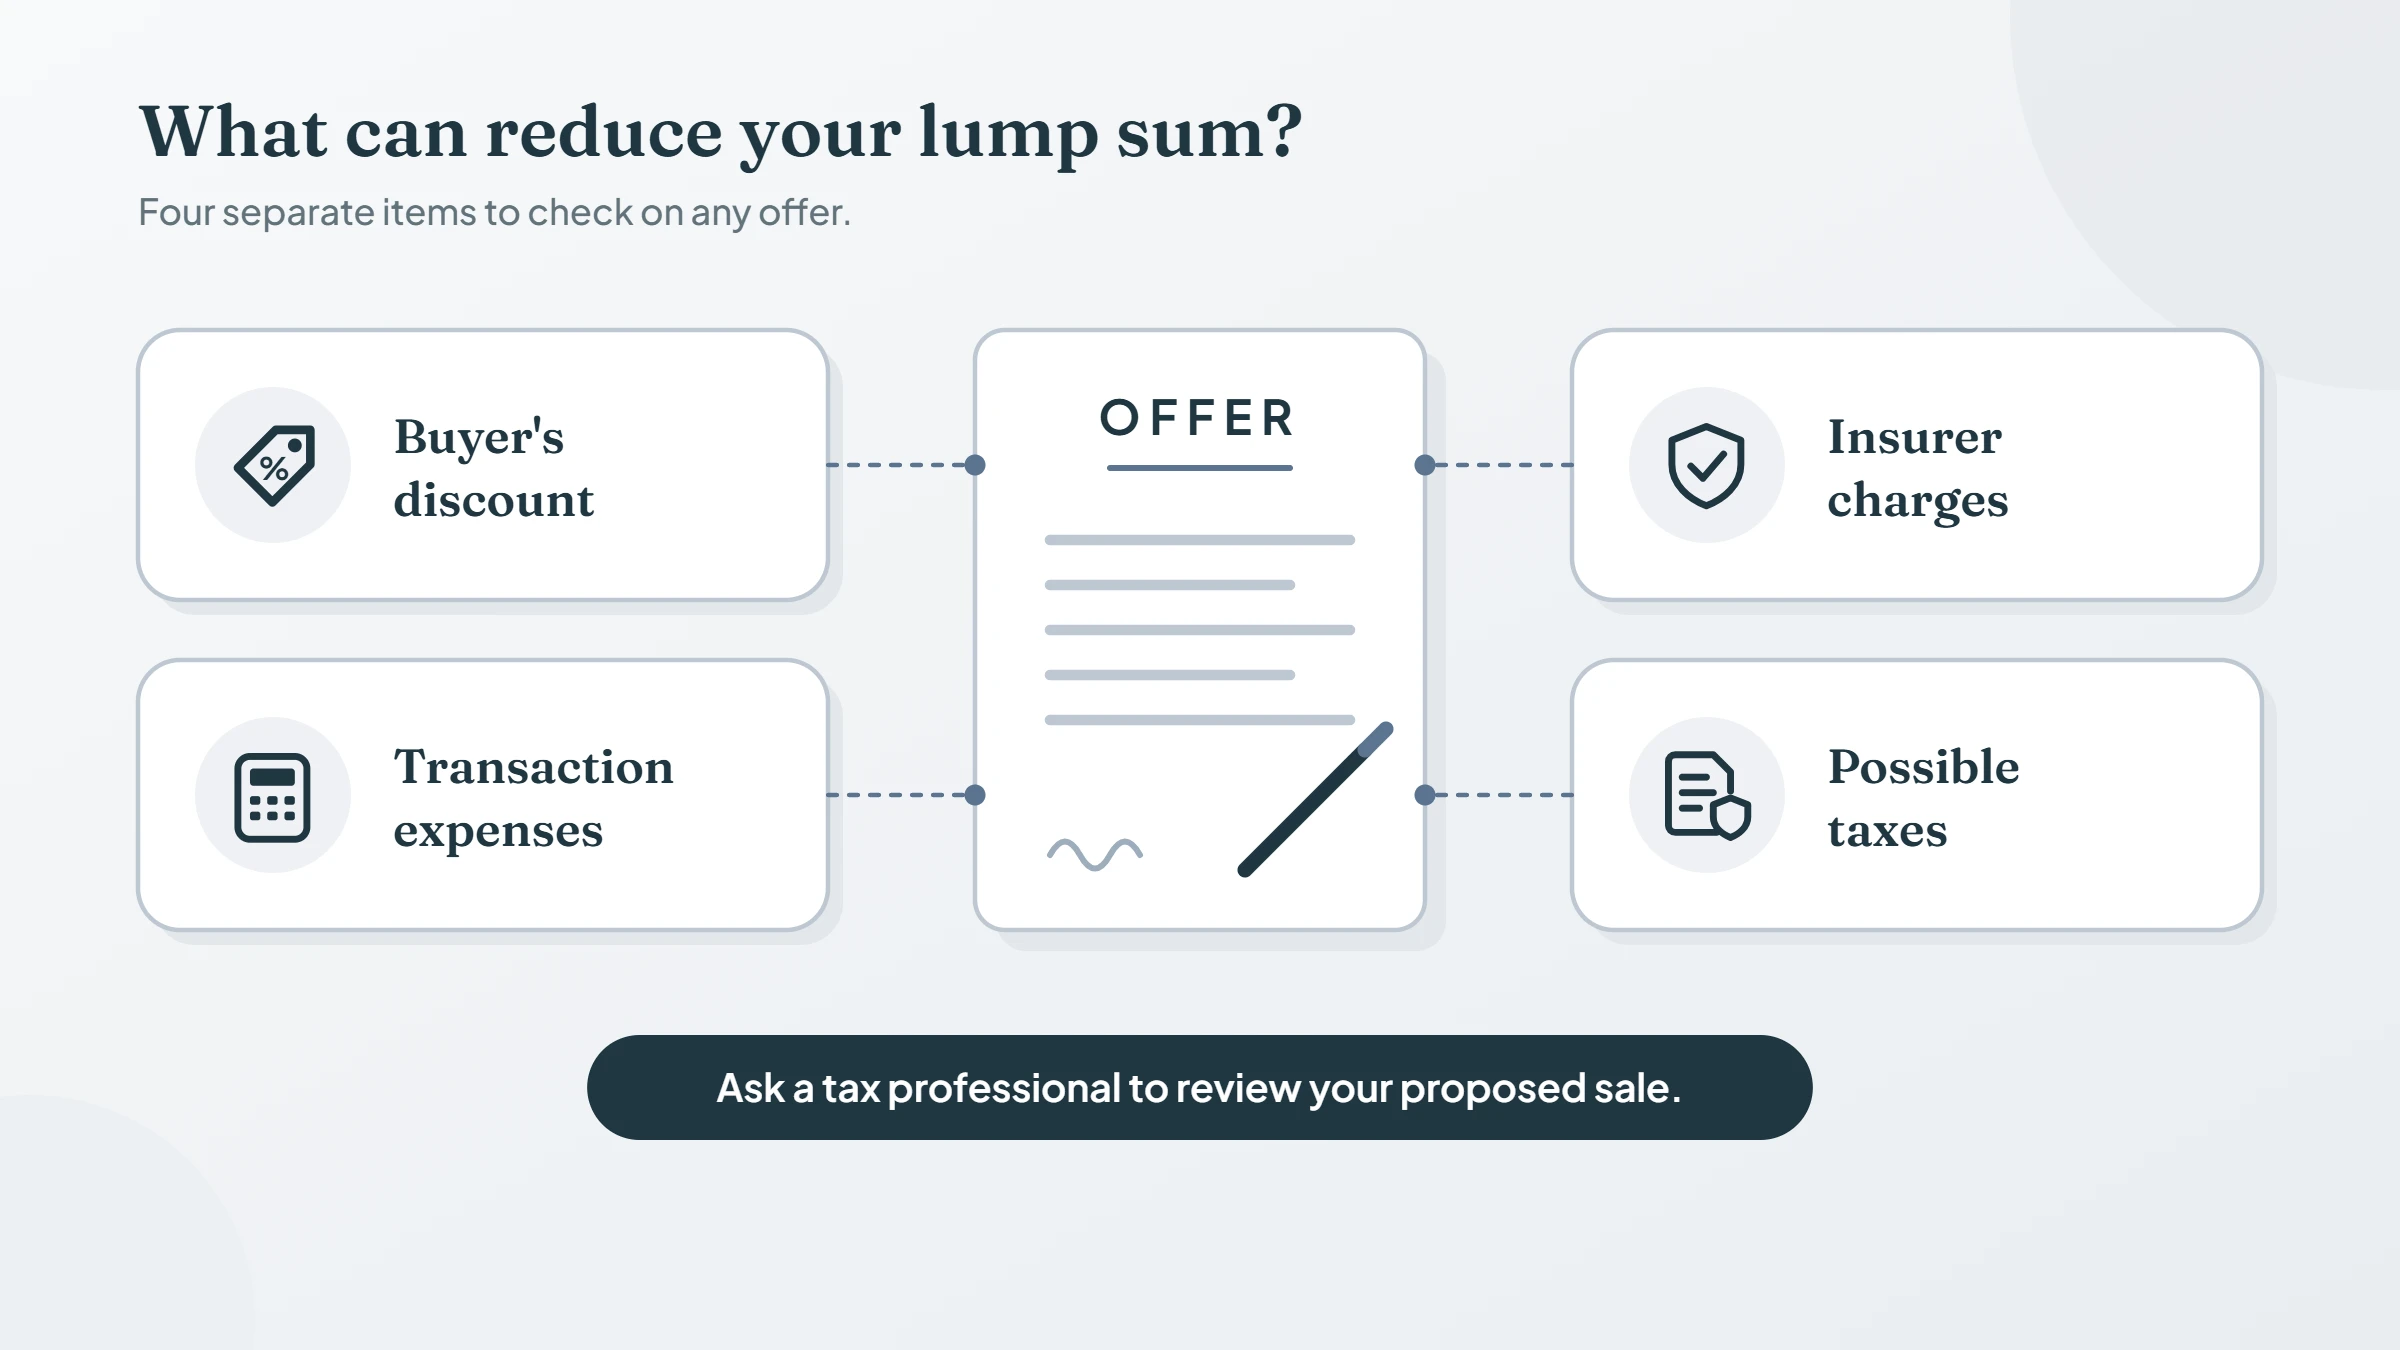
Selling should not be presented as a guaranteed way to avoid surrender charges or taxes. First, establish what transaction is proposed and which costs actually apply.
Tax treatment depends on the annuity and transaction. The IRS explains that gain attributable to accumulated interest on an annuity contract sold before maturity is ordinary income. That does not mean every dollar received in every sale is taxable.
An additional tax can also apply to certain early distributions, although exceptions exist. Age alone does not establish the tax bill for a proposed sale.
Have a qualified tax professional review the documents before signing, particularly for inherited annuities or retirement arrangements.
Questions to Ask Before Accepting an Offer
- Will I have enough income after the sale?
- What payments and benefits could my family lose?
- Does the insurer offer a withdrawal, surrender, or other option?
- What is my net cash amount after transaction costs?
- What taxes could apply?
- What approvals and cancellation terms govern this agreement?
A sale can address an immediate need, but the future income you transfer may have supported you for years.
Discuss Your Annuity With MySettlement
MySettlement purchases eligible annuity payment rights for a discounted lump sum. Share your documents and payment schedule so we can review the arrangement and discuss a potential offer.
Explore selling your annuity payments
This guide provides general information, not individual legal, tax, or financial advice.
Frequently Asked Questions
Can I sell only a few payments?
Possibly. Partial sales depend on your payment rights, contract terms, buyer, and applicable requirements.
Do I always need court approval?
No single approval process applies to every annuity. Structured settlement transfers generally involve court review; other arrangements require their own assessment.
How long does selling take?
Timing varies with document availability, insurer requirements, legal approvals, and closing conditions. Ask for an estimate based on your specific transaction.